Form W-9 gives you the contractor's legal name, tax classification, and Taxpayer Identification Number: everything you need to file an accurate 1099. Collect it before the first payment, not at year-end.
Last updated:
October 2026
What is Form W-9 and why do you need it?
Form W-9, Request for Taxpayer Identification Number and Certification, is the form a contractor or other non-employee payee completes and returns to you. It gives you two things you need to file a 1099 accurately: their legal name and their Taxpayer Identification Number (TIN).
The W-9 itself is never submitted to the IRS. It stays in your files. You use the information on it to populate the 1099 you file with the IRS and furnish to the contractor at year-end.
Without a completed, valid W-9, you cannot file an accurate 1099. And without a valid W-9, you are generally required to withhold 24 percent of all payments to that contractor and remit it to the IRS as backup withholding.
When should you collect a W-9?
Collect a W-9 before the first payment, not at year-end. Once you have made payments, chasing a W-9 from a contractor you no longer need is far more difficult.
There is no IRS dollar threshold for W-9 collection. You do not wait to see whether the contractor will cross the reporting threshold before requesting the form. The threshold determines whether you file a 1099 at year-end, but it does not determine when you collect the W-9.
This matters especially under the current $2,000 reporting threshold for the 2026 tax year. You may start a project expecting to pay a contractor $1,500 (below the threshold) and later expand the scope. If total payments cross $2,000 and you have no W-9 on file, you face a filing problem and potential backup withholding liability retroactively.
Build W-9 collection into your contractor onboarding process. Request it alongside your contract or statement of work, before any work begins.
What does a W-9 ask for?
The form collects the contractor's identifying information and a certification of their TIN accuracy. Here is what each section covers.
| Field | What the contractor enters | Why it matters |
|---|
| Line 1: Name | Legal name as it appears on their tax return. For a sole proprietor or single-member LLC, this is the owner's name, not a business trade name. | Used on the 1099. Must match IRS records to avoid TIN mismatch. |
| Line 2: Business name | DBA or trade name, if different from Line 1. Optional if the entity name on Line 1 is the full operating name. | Optional; helps match invoices to the correct payee record. |
| Line 3: Federal tax classification | Check one: individual/sole proprietor, C corporation, S corporation, partnership, trust/estate, LLC (with tax classification), or other. | Determines whether a 1099 is required (corporations are generally exempt). |
| Lines 5-6: Address | Street address, city, state, and ZIP for mailing the recipient copy of the 1099. | Required for mailing Copy B to the recipient. |
| Part I: TIN | Social Security Number (SSN) for individuals and sole proprietors; Employer Identification Number (EIN) for corporations, partnerships, and multi-member LLCs. | Goes directly on the 1099. A wrong TIN triggers backup withholding and potential IRS penalties. |
| Part II: Certification | Contractor's signature, certifying that their TIN is correct and that they are not subject to backup withholding. | Unsigned W-9s are not valid. The signature certifies accuracy under penalties of perjury. |
Sole proprietors and single-member LLCs must enter the owner's SSN in Part I, not an EIN. This is one of the most common W-9 errors. A sole proprietor who uses an EIN instead of their SSN creates a TIN mismatch that can trigger a CP2100 notice and backup withholding.
How do you request a W-9?
There is no official IRS procedure for how to request a W-9. You download the current version of the form from IRS.gov and send it to the contractor with instructions to complete, sign, and return it to you before you issue payment.
You can send it by email, include it in your contractor onboarding packet, or use a document management platform that supports electronic completion. Electronic signatures are acceptable. The IRS does not require a wet signature on a W-9.
Make the request straightforward. Tell the contractor what the form is, why you need it, and what happens if they do not provide it: you are required by law to withhold 24 percent of their payments as backup withholding until a valid W-9 is on file.
What if a contractor refuses to provide a W-9?
If a contractor declines to provide a W-9, you must begin backup withholding immediately. Withhold 24 percent of every payment and remit it to the IRS. File Form 945, Annual Return of Withheld Federal Income Tax, to report the withheld amounts at year-end.
You still file a 1099 at year-end if payments meet the reporting threshold. Without a TIN from the contractor, enter all zeros in the TIN field on the 1099. This will trigger an IRS notice, but it documents that you made a good-faith attempt to comply.
In practice, backup withholding at 24 percent is a strong motivator. Most contractors provide a W-9 once they understand that the alternative is a 24 percent reduction on every payment they receive from you.
Document your request in writing: the date you sent it and the contractor's response. If the IRS later questions your backup withholding compliance, a paper trail showing a timely, documented solicitation is your defense.
How do you verify the information on the W-9?
Review the completed W-9 before accepting it. Check four things:
- The name on Line 1 matches what the contractor uses on their tax return.
- The federal tax classification on Line 3 is checked. This tells you whether a 1099 is required at all. Corporations are generally exempt, with two exceptions: attorney fees and medical or health care payments.
- The TIN in Part I is complete and formatted correctly. An SSN is nine digits in the format XXX-XX-XXXX. An EIN is nine digits in the format XX-XXXXXXX.
- Part II is signed. An unsigned W-9 is not valid.
Beyond review, run the name and TIN combination through the IRS TIN Matching program before filing your 1099s. TIN Matching is a free IRS service available through e-Services at IRS.gov. It validates that the name and TIN on the W-9 match IRS records before you file, which is the most effective way to prevent CP2100 (B-Notice) penalties.
How long do you keep a W-9?
Keep each W-9 for at least four years after the date of the associated tax return. For contractors with whom you have an ongoing relationship, many tax advisors recommend keeping the form indefinitely or requesting a fresh one every few years to ensure the information is still current.
You are not required to submit the W-9 to the IRS under normal circumstances. It is an internal record that supports your 1099 filings. If the IRS examines your information return compliance, you may be asked to produce W-9s to demonstrate that you exercised proper due diligence.
When do you need to collect a new W-9?
You do not need to collect a new W-9 every year for the same contractor. However, request an updated form when:
- The contractor's name changes due to marriage, divorce, or a business restructuring.
- The contractor's TIN changes, for example, if they incorporate and switch from an SSN to an EIN.
- The contractor's tax classification changes, for example, if a sole proprietor forms an LLC and elects corporate taxation.
- You receive a B-Notice (CP2100) from the IRS indicating a name and TIN mismatch on a prior filing. A first B-Notice requires you to solicit a corrected W-9 within 15 business days.
As a general best practice, request a new W-9 from active contractors every three to five years. Changes in business structure are common and not always communicated proactively.
Does the $2,000 reporting threshold change when you collect a W-9?
No. The reporting threshold for the 2026 tax year determines whether you file a 1099-NEC for a given contractor. It does not change your W-9 collection policy.
Collect a W-9 from every contractor before the first payment, regardless of how much you expect to pay them. The threshold is applied at year-end when you determine who receives a 1099. Your W-9 collection process happens at onboarding.
For more on how the reporting threshold works, see 1099-NEC Reporting Threshold: When You Must File for Contractor Payments.
How does the W-9 connect to your 1099 filing in Adams Tax Forms Helper?
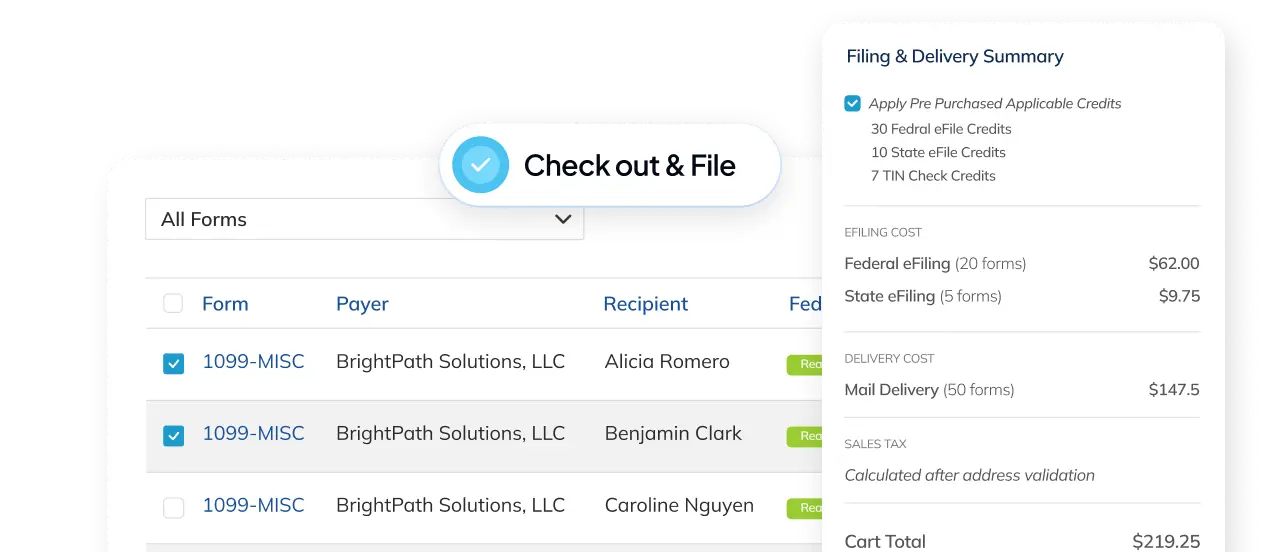
When you are ready to file, the information on the W-9 flows directly into your 1099-NEC or 1099-MISC in Adams® Tax Forms Helper®. Enter the contractor's name exactly as it appears on Line 1 of their W-9, and enter their TIN from Part I. The name and TIN must match what the contractor has on file with the IRS. Any difference can result in a CP2100 notice.
See Adding, Editing, or Deleting a 1099-NEC for instructions on entering contractor information, and About eFiling to file your 1099s with the IRS.
Collect the W-9 before the first payment. Verify the TIN before you file. The rest is straightforward.
Subject to change. Verify at IRS.gov or the relevant government site.
FAQs
When should you collect a W-9 from a contractor?
Before the first payment, not at year-end. There is no IRS dollar threshold for W-9 collection, so you do not wait to see whether a contractor will cross the reporting threshold. Build the request into onboarding, alongside your contract or statement of work, before any work begins.
Do you send Form W-9 to the IRS?
No. The W-9 is never submitted to the IRS under normal circumstances; it stays in your files as the internal record supporting your 1099 filings. You use the name and TIN on it to populate the 1099 you file and furnish at year-end. If the IRS examines your information return compliance, you may be asked to produce W-9s to show due diligence.
What happens if a contractor refuses to provide a W-9?
You must begin backup withholding immediately, withholding 24 percent of every payment and remitting it to the IRS, then reporting the amounts on Form 945 at year-end. You still file a 1099 if payments meet the reporting threshold; without a TIN from the contractor, enter all zeros in the TIN field. Document the date you sent the request and the response, because a timely documented solicitation is your defense.
How long do you keep a W-9 on file?
At least four years after the date of the associated tax return. For ongoing contractor relationships, many tax advisors recommend keeping the form indefinitely or requesting a fresh one every three to five years so the information stays current. Request a new W-9 when a contractor's name, TIN, or tax classification changes, or when you receive a CP2100 B-Notice.