What is Form W-2c?
Form W-2c is a corrected version of Form W-2. You use it to fix errors in a W-2 you already filed with the Social Security Administration (SSA) and issued to an employee. It does not replace the original W-2. It shows the previously reported figures alongside the corrected ones so the SSA can update its records.
The W-2c goes to the SSA, not the IRS. That is the same destination as the original W-2. Along with the W-2c, you file Form W-3c, the Transmittal of Corrected Wage and Tax Statements, which summarizes the corrections.
The current version of the form is Form W-2c (Rev. 1-2026). That is what you use for any W-2c filed in 2026 or later, regardless of which tax year you are correcting.
When do you need to file a W-2c?
File a W-2c any time you discover a material error on a W-2 after you have already filed it with the SSA. Common situations include:
- Wrong wage amounts in Box 1
- Incorrect federal, Social Security, or Medicare tax withholding
- Wrong employee name or Social Security number (SSN)
- Incorrect Box 12 code amounts (401(k) deferrals, HSA contributions, employer health coverage cost)
- Wrong state wages or state tax withheld
- A W-2 filed for the wrong employee
There is no statutory deadline for filing a W-2c. File it as soon as you find the error. Waiting creates downstream problems: the employee cannot file an accurate tax return, and the SSA cannot credit the correct earnings to the employee's record.
Do not write 'corrected' or 'amended' on the W-2c form itself. The SSA's systems do not use that language and it can cause processing problems. The CORRECTED checkbox on the form handles the designation automatically.
What errors require a W-2c and which do not?
| Error type | Use W-2c? | Employee impact |
|---|
| Wrong wage or compensation amount (Box 1) | Yes | May need to amend tax return |
| Wrong federal income tax withheld (Box 2) | Yes | May need to amend tax return |
| Wrong Social Security or Medicare wages or taxes (Boxes 3, 4, 5, 6) | Yes | Affects SSA earnings record; may affect benefits |
| Wrong employee name or SSN | Yes | SSA earnings credit may be misposted; must be corrected promptly |
| Wrong employer EIN | File W-3c only | No direct employee impact |
| Wrong Box 12 code amount (401k, HSA, etc.) | Yes | May affect contribution limit calculations on their return |
| Typo in employer name or address only (no dollar corrections) | Generally no SSA filing needed | Provide corrected copy to employee for their records |
A correction to employer name or address only, with no changes to any dollar amounts or employee identification data, generally does not require a new SSA filing. Provide the corrected copy directly to the employee for their records. If you are unsure whether an error rises to the level of requiring a W-2c, err on the side of filing one.
How does the W-2c work? What you enter on the form
The W-2c shows two sets of figures side by side: Previously reported and Correct information. You only fill in the boxes where a correction is being made.
Only complete boxes that contain errors. Leave all other boxes blank. Do not re-enter amounts that were correct on the original W-2. Entering correct amounts in the wrong fields can introduce new errors into the SSA's records.
For each box you are correcting, enter what appeared on the original W-2 in the 'Previously reported' column, then enter the accurate figure in the 'Correct information' column. The SSA uses the difference to update the employee's account.
Box 12 corrections follow the same pattern. Enter the code and the previously reported dollar amount, then enter the code and the corrected amount. If you are adding a Box 12 entry that was missing entirely, leave the 'Previously reported' field blank and enter the correct amount in the correction column.
What is Form W-3c and when do you file it?
Form W-3c, Transmittal of Corrected Wage and Tax Statements, accompanies every paper W-2c you send to the SSA. It summarizes the totals from all your W-2c forms in the same mailing.
File a W-3c whenever you file a paper W-2c, even if you are only correcting a name or SSN with no dollar changes. There are no exceptions to this requirement for paper filers.
If you eFile your W-2c through Adams® Tax Forms Helper®, Form W-3c is generated and transmitted automatically. You do not prepare it separately.
If you are correcting an employer EIN error only, file a W-3c without any W-2c forms. The W-3c is the correct vehicle for that specific correction.
Do you need to eFile a W-2c?
The same 10-return aggregate rule that applies to original W-2 filings applies to W-2c filings. If you expect to file 10 or more W-2c forms during a calendar year, you must eFile all of them. The 10-return count is specific to W-2c volume for purposes of this rule.
If you paper file when eFile is required, the SSA may reject your submission. File a waiver request on Form 8508 before filing if paper filing would create a genuine hardship.
Do not print a W-2c from IRS.gov and mail it to the SSA. The SSA cannot process plain-paper forms printed from IRS.gov. For paper filing, use pre-printed scannable forms. For electronic filing, use an authorized eFile provider such as Tax Forms Helper or the SSA's W-2c Online service.
Where do you send paper W-2c and W-3c forms?
Send paper W-2c and W-3c forms to:
Social Security Administration
Direct Operations Center
Wilkes-Barre, PA 18769-0001
(For Certified Mail: ZIP code 18769-0002)
Do not staple the W-2c forms to the W-3c. Do not fold them. The SSA processes these by machine and physical damage interferes with scanning.
What do you give to the employee?
Furnish a corrected Copy B to the employee as soon as possible after you discover the error. You can send it by mail or, if you have the employee's consent on file, deliver it electronically.
The corrected Copy B will show 'CORRECTED' at the top. The employee should keep it for their records and use it if they need to file an amended federal tax return.
If the correction changes Box 1 (wages) or Box 2 (federal income tax withheld), the employee will almost certainly need to file Form 1040-X, Amended U.S. Individual Income Tax Return, to correct their own return. Notify the employee of this when you send the corrected copy.
If the correction only affects Boxes 3 through 6 (Social Security and Medicare wages and taxes), the employee's federal income tax return is generally not affected. The correction matters for SSA earnings records and for any Social Security tax credit claims, but not for the income tax calculation itself.
Can you correct a W-2c with another W-2c?
Yes. If you discover an error on a previously filed W-2c, file a new W-2c to correct it. Use the same format: enter the amounts from the incorrect W-2c in the 'Previously reported' column and the accurate amounts in the 'Correct information' column.
The corrected W-2c should reference the same tax year as the original W-2 you are ultimately correcting. The SSA layers corrections chronologically, so you do not need to worry about undoing the prior W-2c explicitly. The most recent W-2c for a given employee and tax year governs.
What about state W-2c corrections?
State requirements for W-2c corrections vary. Some states require you to file a corrected wage statement with the state tax authority whenever you correct Boxes 15 through 20 (state and local information). Other states accept a copy of the federal W-2c.
Check the requirements for every state where the employee worked or where your business operates. Do not assume the federal W-2c satisfies state obligations automatically.
How to file a W-2c in Adams Tax Forms Helper
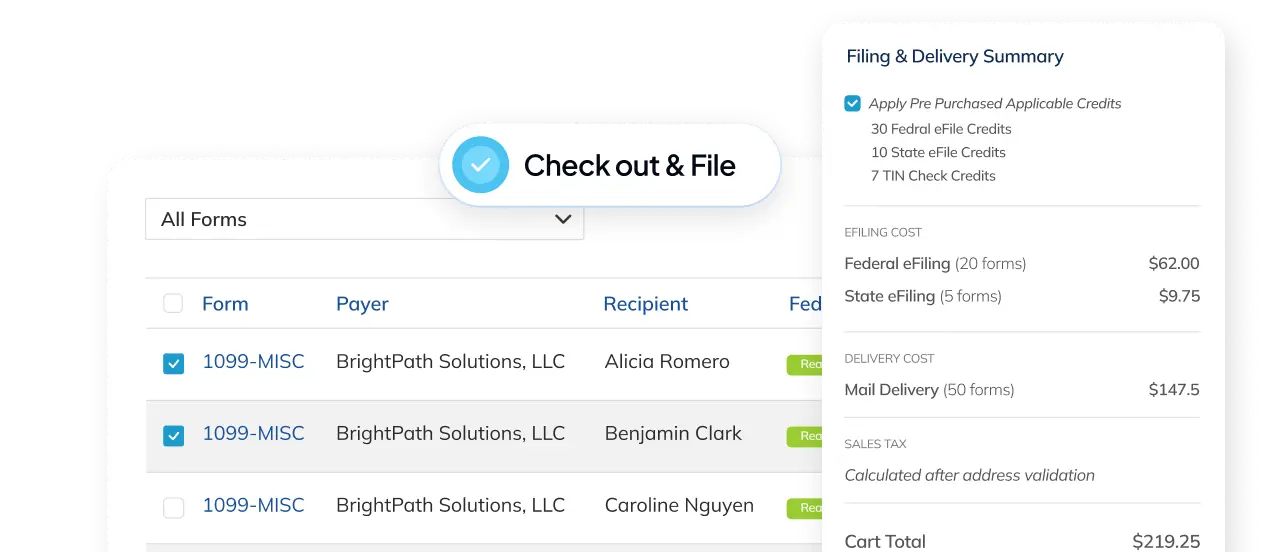
Adams® Tax Forms Helper® supports W-2c eFiling directly to the SSA. Find the original W-2 record, open the correction workflow, enter the previously reported amounts and the corrected amounts in the applicable boxes, and eFile. Tax Forms Helper generates and transmits Form W-3c automatically.
See Correct and eFile a W-2 (W-2C) for step-by-step instructions.
Your correction is filed with the SSA and your employee has an accurate copy. You're done.
FAQ
When do you have to file a Form W-2c?
File a W-2c whenever you find a material error on a W-2 you have already filed with the SSA. That includes wrong wage amounts, incorrect federal, Social Security, or Medicare withholding, a wrong employee name or Social Security number, incorrect Box 12 code amounts, wrong state wages, or a W-2 filed for the wrong employee.
Is there a deadline for filing a W-2c?
No statutory deadline applies, but waiting creates problems. Until the correction is filed, the employee cannot file an accurate tax return and the SSA cannot credit the correct earnings to their record. File it as soon as you discover the error.
Do you need to file Form W-3c with a W-2c?
Yes, for paper filings. Form W-3c, Transmittal of Corrected Wage and Tax Statements, must accompany every paper W-2c you send to the SSA, even if you are only correcting a name or SSN with no dollar changes. If you eFile through Adams Tax Forms Helper, the W-3c is generated and transmitted automatically. To correct an employer EIN error only, file a W-3c with no W-2c forms.
Which boxes do you complete on a Form W-2c?
Only the boxes that contain errors. For each one, enter the figure from the original W-2 in the 'Previously reported' column and the accurate figure in the 'Correct information' column, and leave every other box blank. Do not re-enter amounts that were already correct, because entering correct amounts in the wrong fields can introduce new errors into the SSA's records.
Subject to change. Verify at IRS.gov, SSA.gov, or the relevant government site.
FAQs
When do you have to file a Form W-2c?
File a W-2c whenever you find a material error on a W-2 you have already filed with the SSA. That includes wrong wage amounts, incorrect federal, Social Security, or Medicare withholding, a wrong employee name or Social Security number, incorrect Box 12 code amounts, wrong state wages, or a W-2 filed for the wrong employee.
Is there a deadline for filing a W-2c?
No statutory deadline applies, but waiting creates problems. Until the correction is filed, the employee cannot file an accurate tax return and the SSA cannot credit the correct earnings to their record. File it as soon as you discover the error.
Do you need to file Form W-3c with a W-2c?
Yes, for paper filings. Form W-3c, Transmittal of Corrected Wage and Tax Statements, must accompany every paper W-2c you send to the SSA, even if you are only correcting a name or SSN with no dollar changes. If you eFile through Adams Tax Forms Helper, the W-3c is generated and transmitted automatically. To correct an employer EIN error only, file a W-3c with no W-2c forms.
Which boxes do you complete on a Form W-2c?
Only the boxes that contain errors. For each one, enter the figure from the original W-2 in the 'Previously reported' column and the accurate figure in the 'Correct information' column, and leave every other box blank. Do not re-enter amounts that were already correct, because entering correct amounts in the wrong fields can introduce new errors into the SSA's records.